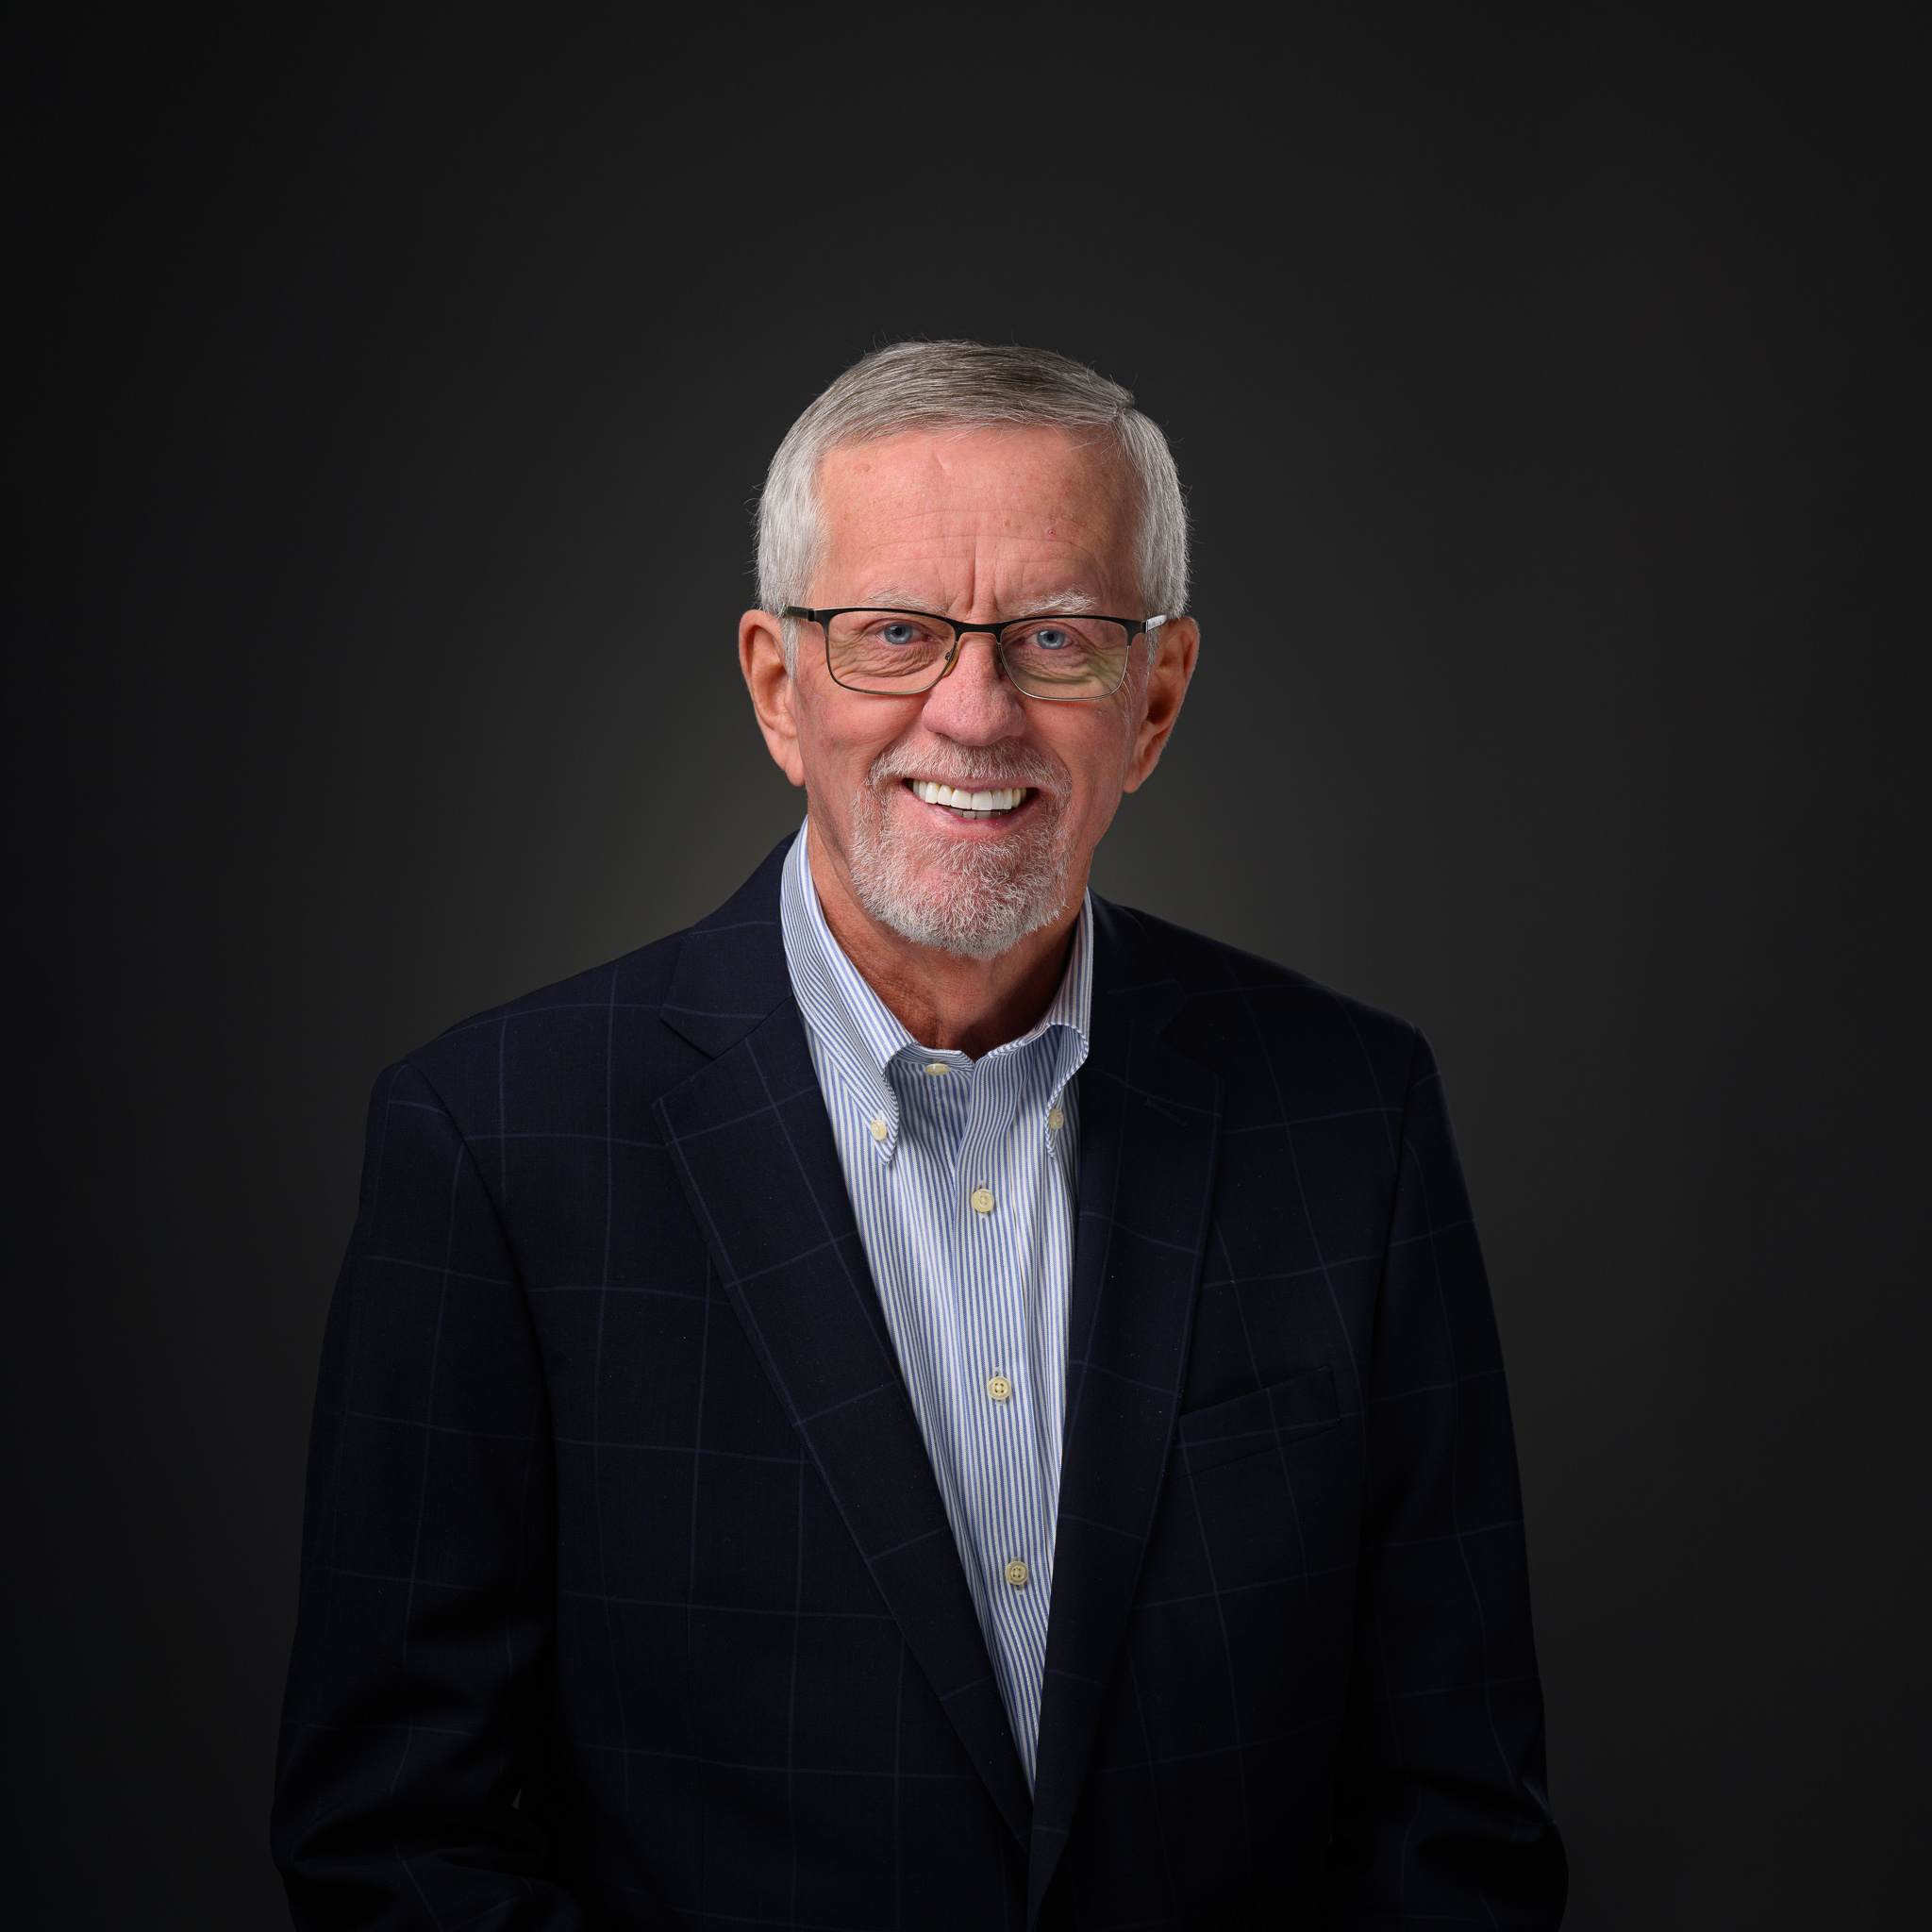
Lavern Rankin Lavern Rankin Senior Partner · Eau Claire Partners

Protection first

See Below For Life Insurance, Explained in Plain Language

The foundation of most family plans: money that arrives exactly when your family needs it most, so they can keep the home, the plans and the life you built together.

TFSA· RRSP· RESP· FHSA· RDSP· LIRA· LIF· RRIF· Pensions

What is life insurance?

Who it's a fit for

Life insurance pays a tax-free benefit to who you choose as your beneficiaries — and beneficiaries aren't limited to people: your estate, your corporation or a charity all work too. Term insurance covers you for a set period at the lowest cost — ideal while the mortgage is big and the kids are young. Whole life covers you for life and builds cash value you can borrow against. Universal life adds investment-style flexibility inside the policy.

Best suited for: Families with a mortgage or young children, anyone whose income others depend on, and people who want to leave something deliberate behind — a legacy, a gift, or liquidity so their estate settles smoothly.
The three main types

Term Life

What makes it different: Covers you for a set period — 10, 20 or 30 years are common — at the lowest cost per dollar of coverage. No cash value: pure protection while your obligations are highest.

Best suited for: Young families with a mortgage and kids at home; covering a specific debt that shrinks over time; anyone wanting maximum coverage on a budget. It's also a very good replacement for the common mortgage insurance presented by banks or mortgage brokers.

Whole Life (PAR & NON PAR)

What makes it different: Permanent — covers you for life as long as premiums are paid — with guaranteed cash value that grows inside the policy and can be borrowed against. Premiums are level for life.

Best suited for: People who want coverage that never expires, final-expense and estate planning, a guaranteed legacy, or the disciplined savings character of permanent coverage.

Universal Life

What makes it different: Permanent coverage with flexibility — within limits you can often adjust premiums and the death benefit, and choose how the policy's investment component is handled.

Best suited for: People who want lifelong protection plus hands-on flexibility and investment options — often part of longer-term planning, including corporate-owned arrangements.

What it can do for you

  • ✓Leaves your loved ones knowing you made a choice for them — one less burden on their hardest day
  • ✓Replaces your income so your family keeps its standard of living
  • ✓Pays off the mortgage and other debts so survivors aren't forced to sell
  • ✓Funds final expenses, taxes and estate costs
  • ✓Creates a legacy — for family, a cause, or the next generation
  • ✓Permanent plans can build cash value you can access while living

Good to know

  • • The right amount comes from a proper needs conversation — not a web calculator
  • • Health and lifestyle affect price, so applying sooner will be cheaper
  • • Most term policies include a conversion privilege — keeping future options open — but details vary by contract

General information, not personal advice — details, eligibility and pricing depend on the insurer and the specific product, and are confirmed before anything is recommended.

Book a conversation

Let's talk about how you can protect and grow what YOU want.

That's exactly what the first conversation is for. We'll size it to your real life — no cost, no obligation.

  • ✓ Your goals
  • ✓ Protection, investments and your tax picture
  • ✓ I will support you and provide you with honest advice at every stage of your journey
  • ✓ If retirement planning is important to you, let's map out a plan

Eau Claire Partners

Lavern Rankin is a Senior Partner with Eau Claire Partners — a full-service financial advisory firm helping Canadians build, protect and transfer their wealth with confidence.

Learn more about Eau Claire Partners