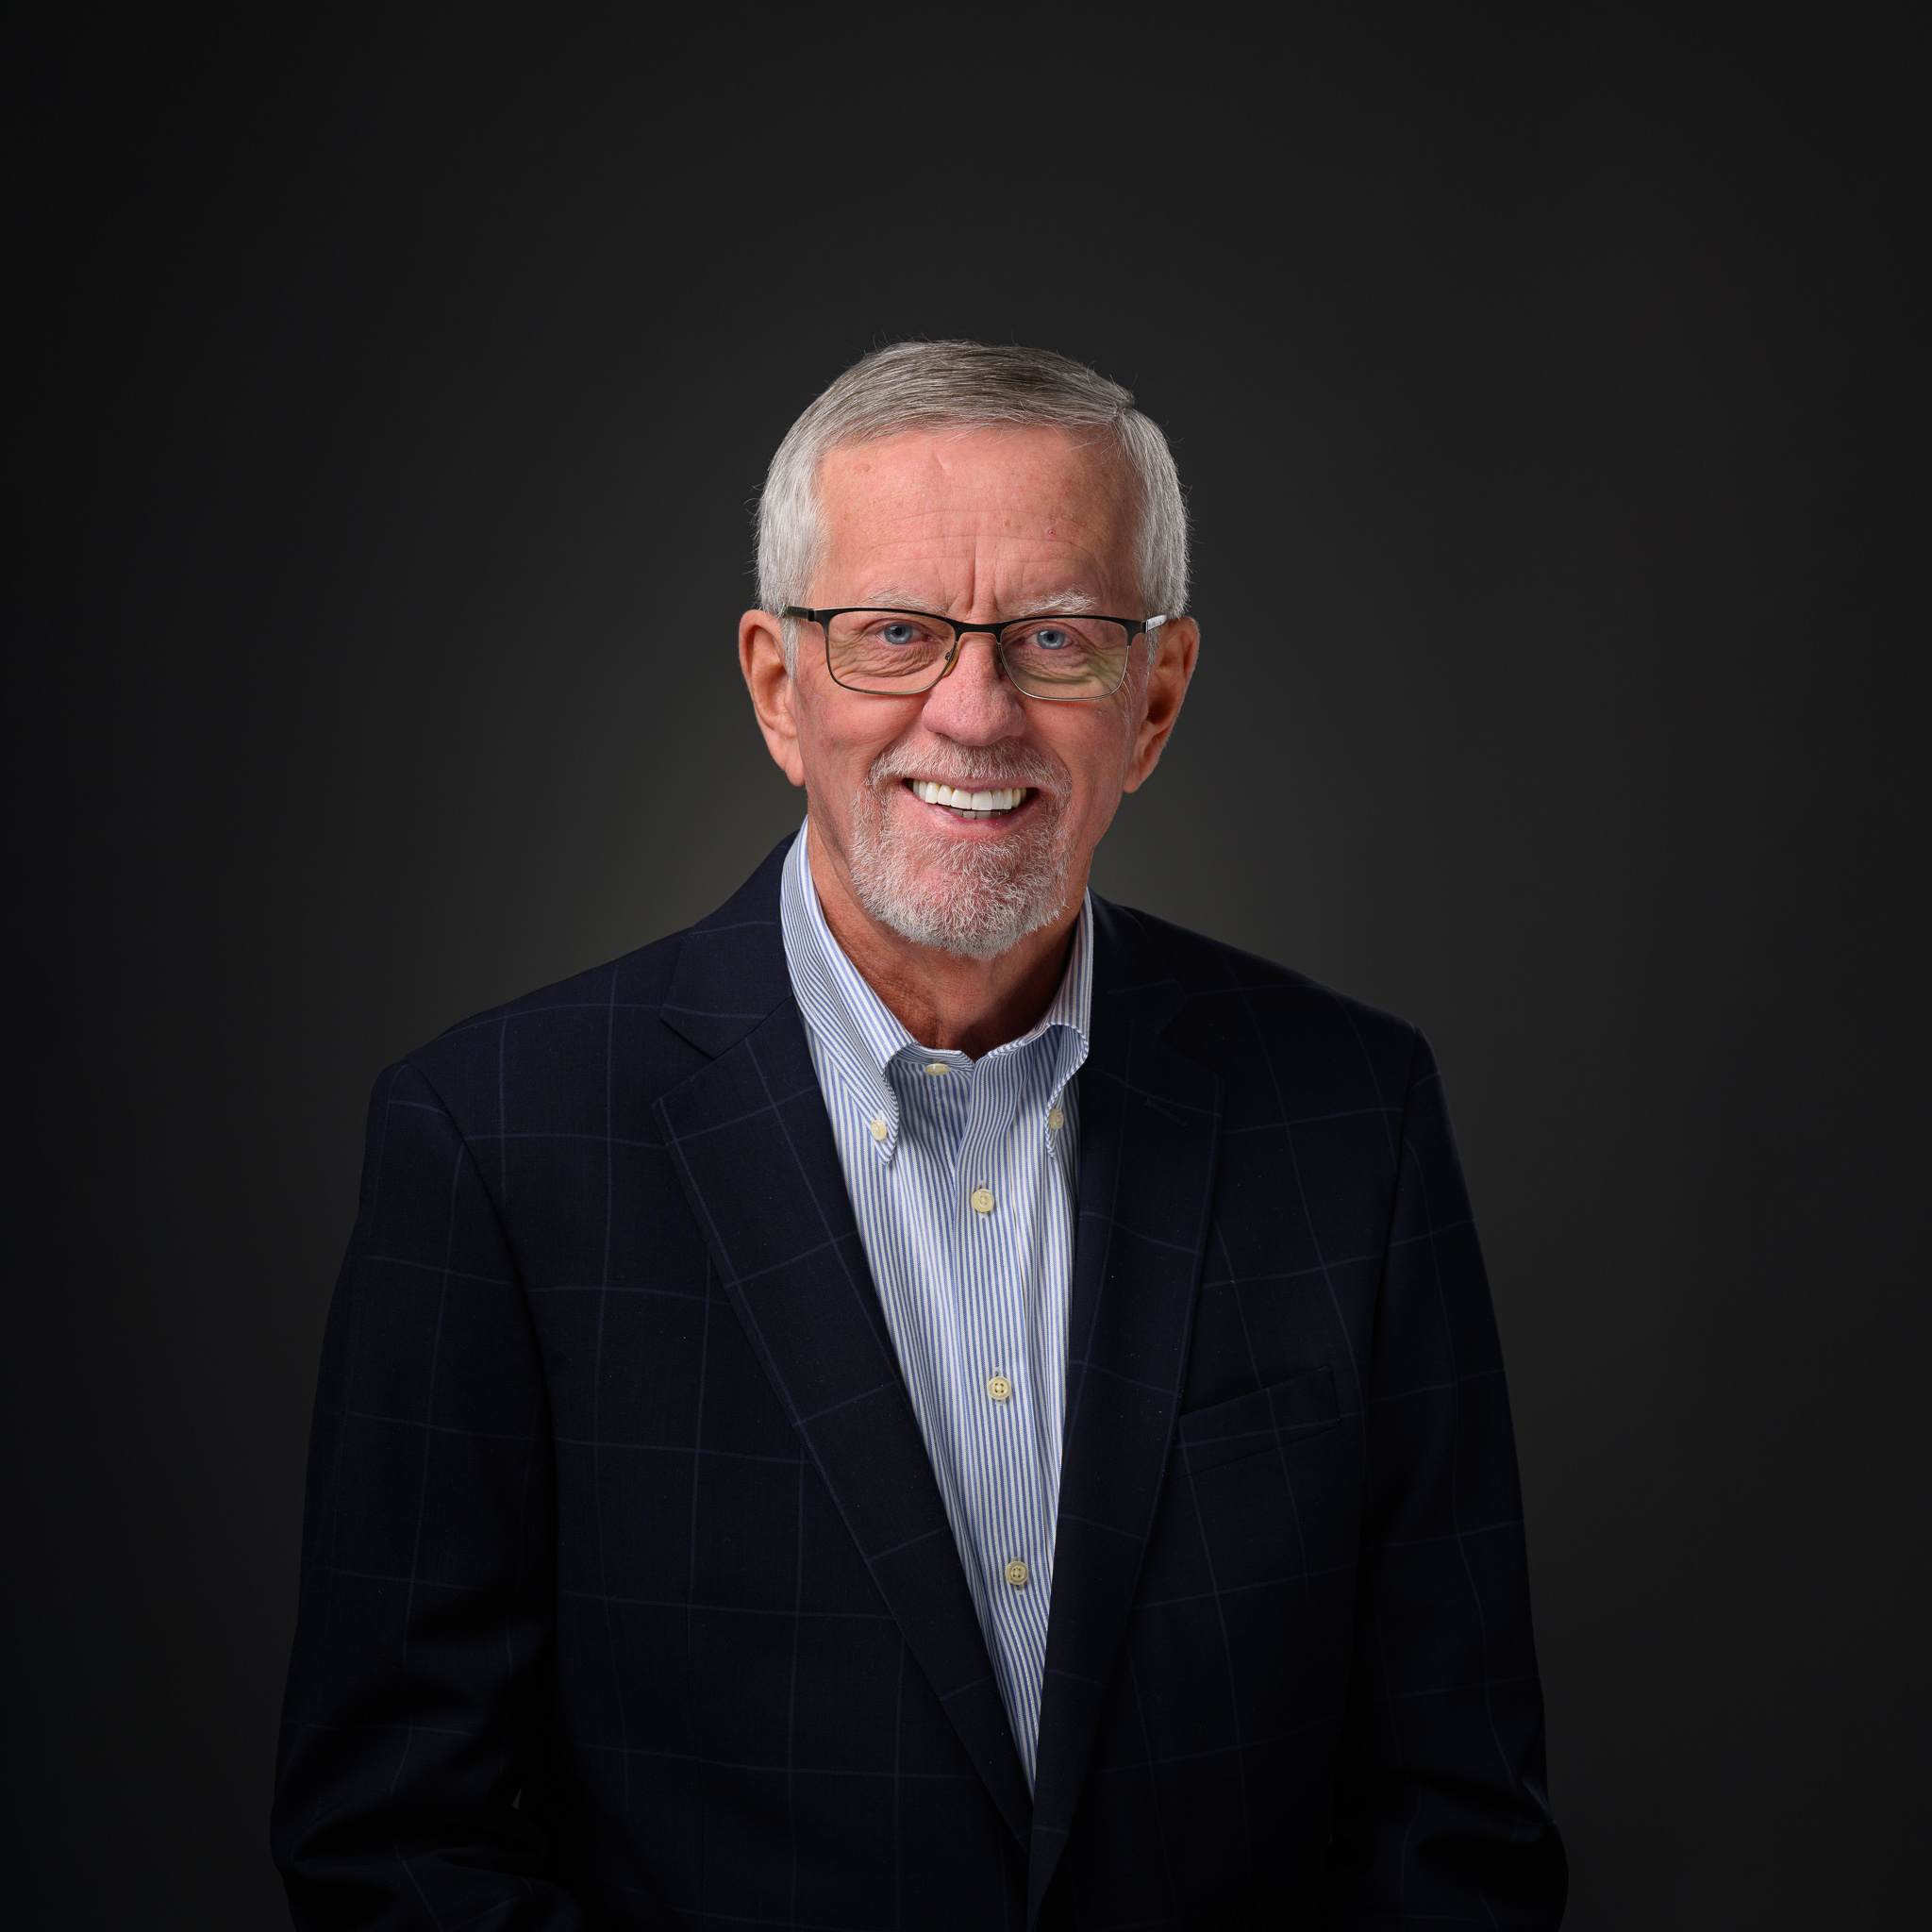
Lavern Rankin Lavern Rankin Senior Partner · Eau Claire Partners

Understanding your options

See Below For TFSA, RRSP, RESP, FHSA, RDSP & RRIF, Explained in Plain Language

Registered accounts are simply wrappers with different tax rules and different jobs. Pick the right wrapper for the right goal, and your money works harder without you doing anything heroic.

Contribution limits and rules change over time — we'll confirm the current numbers for your situation together.

TFSA

Tax-Free Savings Account

What it is

A flexible account where investments grow completely tax-free — and withdrawals are tax-free too, anytime. Unused contribution room carries forward, and anything you withdraw creates new room again the next year.

Best suited for

Almost everyone. Short- and mid-term goals, emergency savings that still grow, retirement top-ups beyond your RRSP, and income that stays invisible to government benefit calculations like OAS.

Good to know

  • • Contributions aren't deductible, but withdrawals never trigger tax
  • • Room accumulates every year you're 18+, whether you contribute or not
  • • Works beautifully with segregated funds for guaranteed-growth investing

Official rules & current limits: Canada.ca — Tax-Free Savings Account (CRA) ↗
RRSP

Registered Retirement Savings Plan

What it is

Canada's classic retirement account. Contributions reduce your taxable income today (often generating a meaningful tax refund), investments grow tax-deferred, and you pay tax only when you withdraw in retirement — ideally at a lower rate.

Best suited for

People in their peak earning years, anyone with a workplace pension gap, and those who want to use spousal RRSPs to split retirement income between partners.

Good to know

  • • Contribution room is based on your income and pension adjustments
  • • The Home Buyers' Plan can help first-time buyers tap RRSP funds
  • • Converts to a RRIF by the end of the year you turn 71

Official rules & current limits: Canada.ca — RRSPs and related plans (CRA) ↗

RESP

Registered Education Savings Plan

What it is

A dedicated education-savings account for a child. The government matches 20% of your contributions through the Canada Education Savings Grant — essentially free money toward tuition, up to annual and lifetime grant limits.

Best suited for

Parents, grandparents and anyone who wants to help a child fund post-secondary education without sacrificing their own retirement savings to do it.

Good to know

  • • Grants are based on family income — lower-income families may qualify for more
  • • Withdrawals for qualifying education are largely taxed in the student's hands
  • • If a child doesn't attend, there are options — we'll walk through them

Official rules, limits & government grants: Canada.ca — RESPs (CRA) ↗ · Government education grants (CESG) ↗

FHSA

First Home Savings Account

What it is

The rare account that gives you both sides of the tax coin: contributions are deductible like an RRSP, and withdrawals to buy your first home are tax-free like a TFSA.

Best suited for

First-time home buyers who can commit to a savings plan — and parents or grandparents helping a young adult reach the down-payment finish line faster.

Good to know

  • • There's a lifetime contribution cap and a 15-year usage window
  • • Unused room can often be transferred to an RRSP without losing room
  • • Works alongside the Home Buyers' Plan — the two stack

Official rules & current limits: Canada.ca — First Home Savings Account (CRA) ↗

RDSP

Registered Disability Savings Plan

What it is

A long-term savings plan for a person eligible for the Disability Tax Credit. Government grants and bonds can add substantially to the savings — making it one of the most generous accounts in the Canadian system.

Best suited for

Families planning for the long-term financial security of a loved one with a disability — often parents and grandparents setting up lifetime support.

Good to know

  • • Eligibility is tied to the Disability Tax Credit certificate
  • • Grants and bonds depend on family income and contributions
  • • Rules around withdrawals and timing are specific — worth doing properly

Official rules, limits & government grants: Canada.ca — RDSPs (CRA) ↗ · Government grants & bonds ↗

LIRA / LIF

Locked-in retirement accounts

What it is

When you leave an employer with a pension, those funds often move into a LIRA — money that stays locked-in until retirement, then converts to a LIF with regulated withdrawal rules.

Best suited for

Anyone who's changed employers and inherited pension money they'd like to invest with intention rather than leave forgotten.

Good to know

  • • Rules vary by province and pension jurisdiction
  • • Investment choices inside a LIRA are fully yours — many people underuse this
  • • Leaving an employment pension? See Pension Choices before you decide what to do with it

Official rules: Canada.ca — RRSPs and related plans (CRA) ↗ — locked-in withdrawal rules also follow provincial pension legislation

RRIF

Registered Retirement Income Fund

What it is

A RRIF is simply an RRSP that's started paying you income. By the end of the year you turn 71, RRSP savings must convert into a RRIF (or be handled another way). Your money stays invested while you draw a government-set minimum amount each year.

Best suited for

Anyone converting RRSP savings into retirement income who still wants their investments working — with a plan for how much to withdraw and when.

Good to know

  • • Withdrawals are taxable income, so the timing and amount matter
  • • Minimum withdrawal percentages are set by the government based on age
  • • Segregated funds can be held inside a RRIF too
  • • Beneficiary designations can help remaining funds settle efficiently

Official rules & minimum withdrawals: Canada.ca — RRIFs (CRA) ↗

Non-registered

Flexible investing

What it is

A plain investment account with no contribution limits and no withdrawal restrictions — the workhorse once your registered room is full, or when flexibility matters most.

Best suited for

Larger balances, mid-term goals, and investors who want room to move. Segregated funds here can add estate and creditor-structure advantages worth discussing.

Good to know

  • • Tax-efficient fund selection matters more here
  • • Pairs well with insurance-based strategies for estate planning

Official tax treatment: Canada.ca — Capital gains & investment income (CRA) ↗

CPP & OAS

Government retirement benefits

What they are

CPP is the earnings-based pension you build through your working years; OAS is the age-based pension most Canadians start receiving at 65. They're government benefits, not accounts — and they interact with everything else in your plan, from when to start each benefit to how OAS gets clawed back at higher incomes.

Best suited for

Everyone planning a retirement income. The real questions are when to start each benefit and how they fit with your RRSP, RRIF and TFSA withdrawals — that's part of the planning conversation, not a form to fill out.

Good to know

  • • Taking CPP early permanently reduces it — deferring increases it
  • • OAS is clawed back once retirement income passes a threshold
  • • Amounts depend on your contribution history and age — we confirm yours together

Official rules: Canada.ca — Canada Pension Plan ↗ · Canada.ca — Old Age Security ↗

Pension Choices

Know your options before you decide

Do you know what options you have?

Depending on your pension plan and circumstances, you may have options such as keeping the pension where it is, transferring it to another eligible plan, or moving eligible funds to a Locked-in Retirement Account (LIRA).

Before making a decision, consider

  • • What are your current options — what level of returns does your pension have, and what happens to the funds if you pass away?
  • • What investment choices are available?
  • • What fees are you paying?
  • • Who is managing the investments?
  • • How can the money fit into your overall retirement plan?

Don't leave your old pension on autopilot without understanding your options — it could be costly. General information, not personal advice.

Book a conversation

Let's talk about how you can protect and grow what YOU want.

That's exactly what the first conversation is for. We'll match the right accounts to your goals — and confirm the numbers that apply today.

  • ✓ Your goals
  • ✓ Protection, investments and your tax picture
  • ✓ I will support you and provide you with honest advice at every stage of your journey
  • ✓ If retirement planning is important to you, let's map out a plan

Eau Claire Partners

Lavern Rankin is a Senior Partner with Eau Claire Partners — a full-service financial advisory firm helping Canadians build, protect and transfer their wealth with confidence.

Learn more about Eau Claire Partners