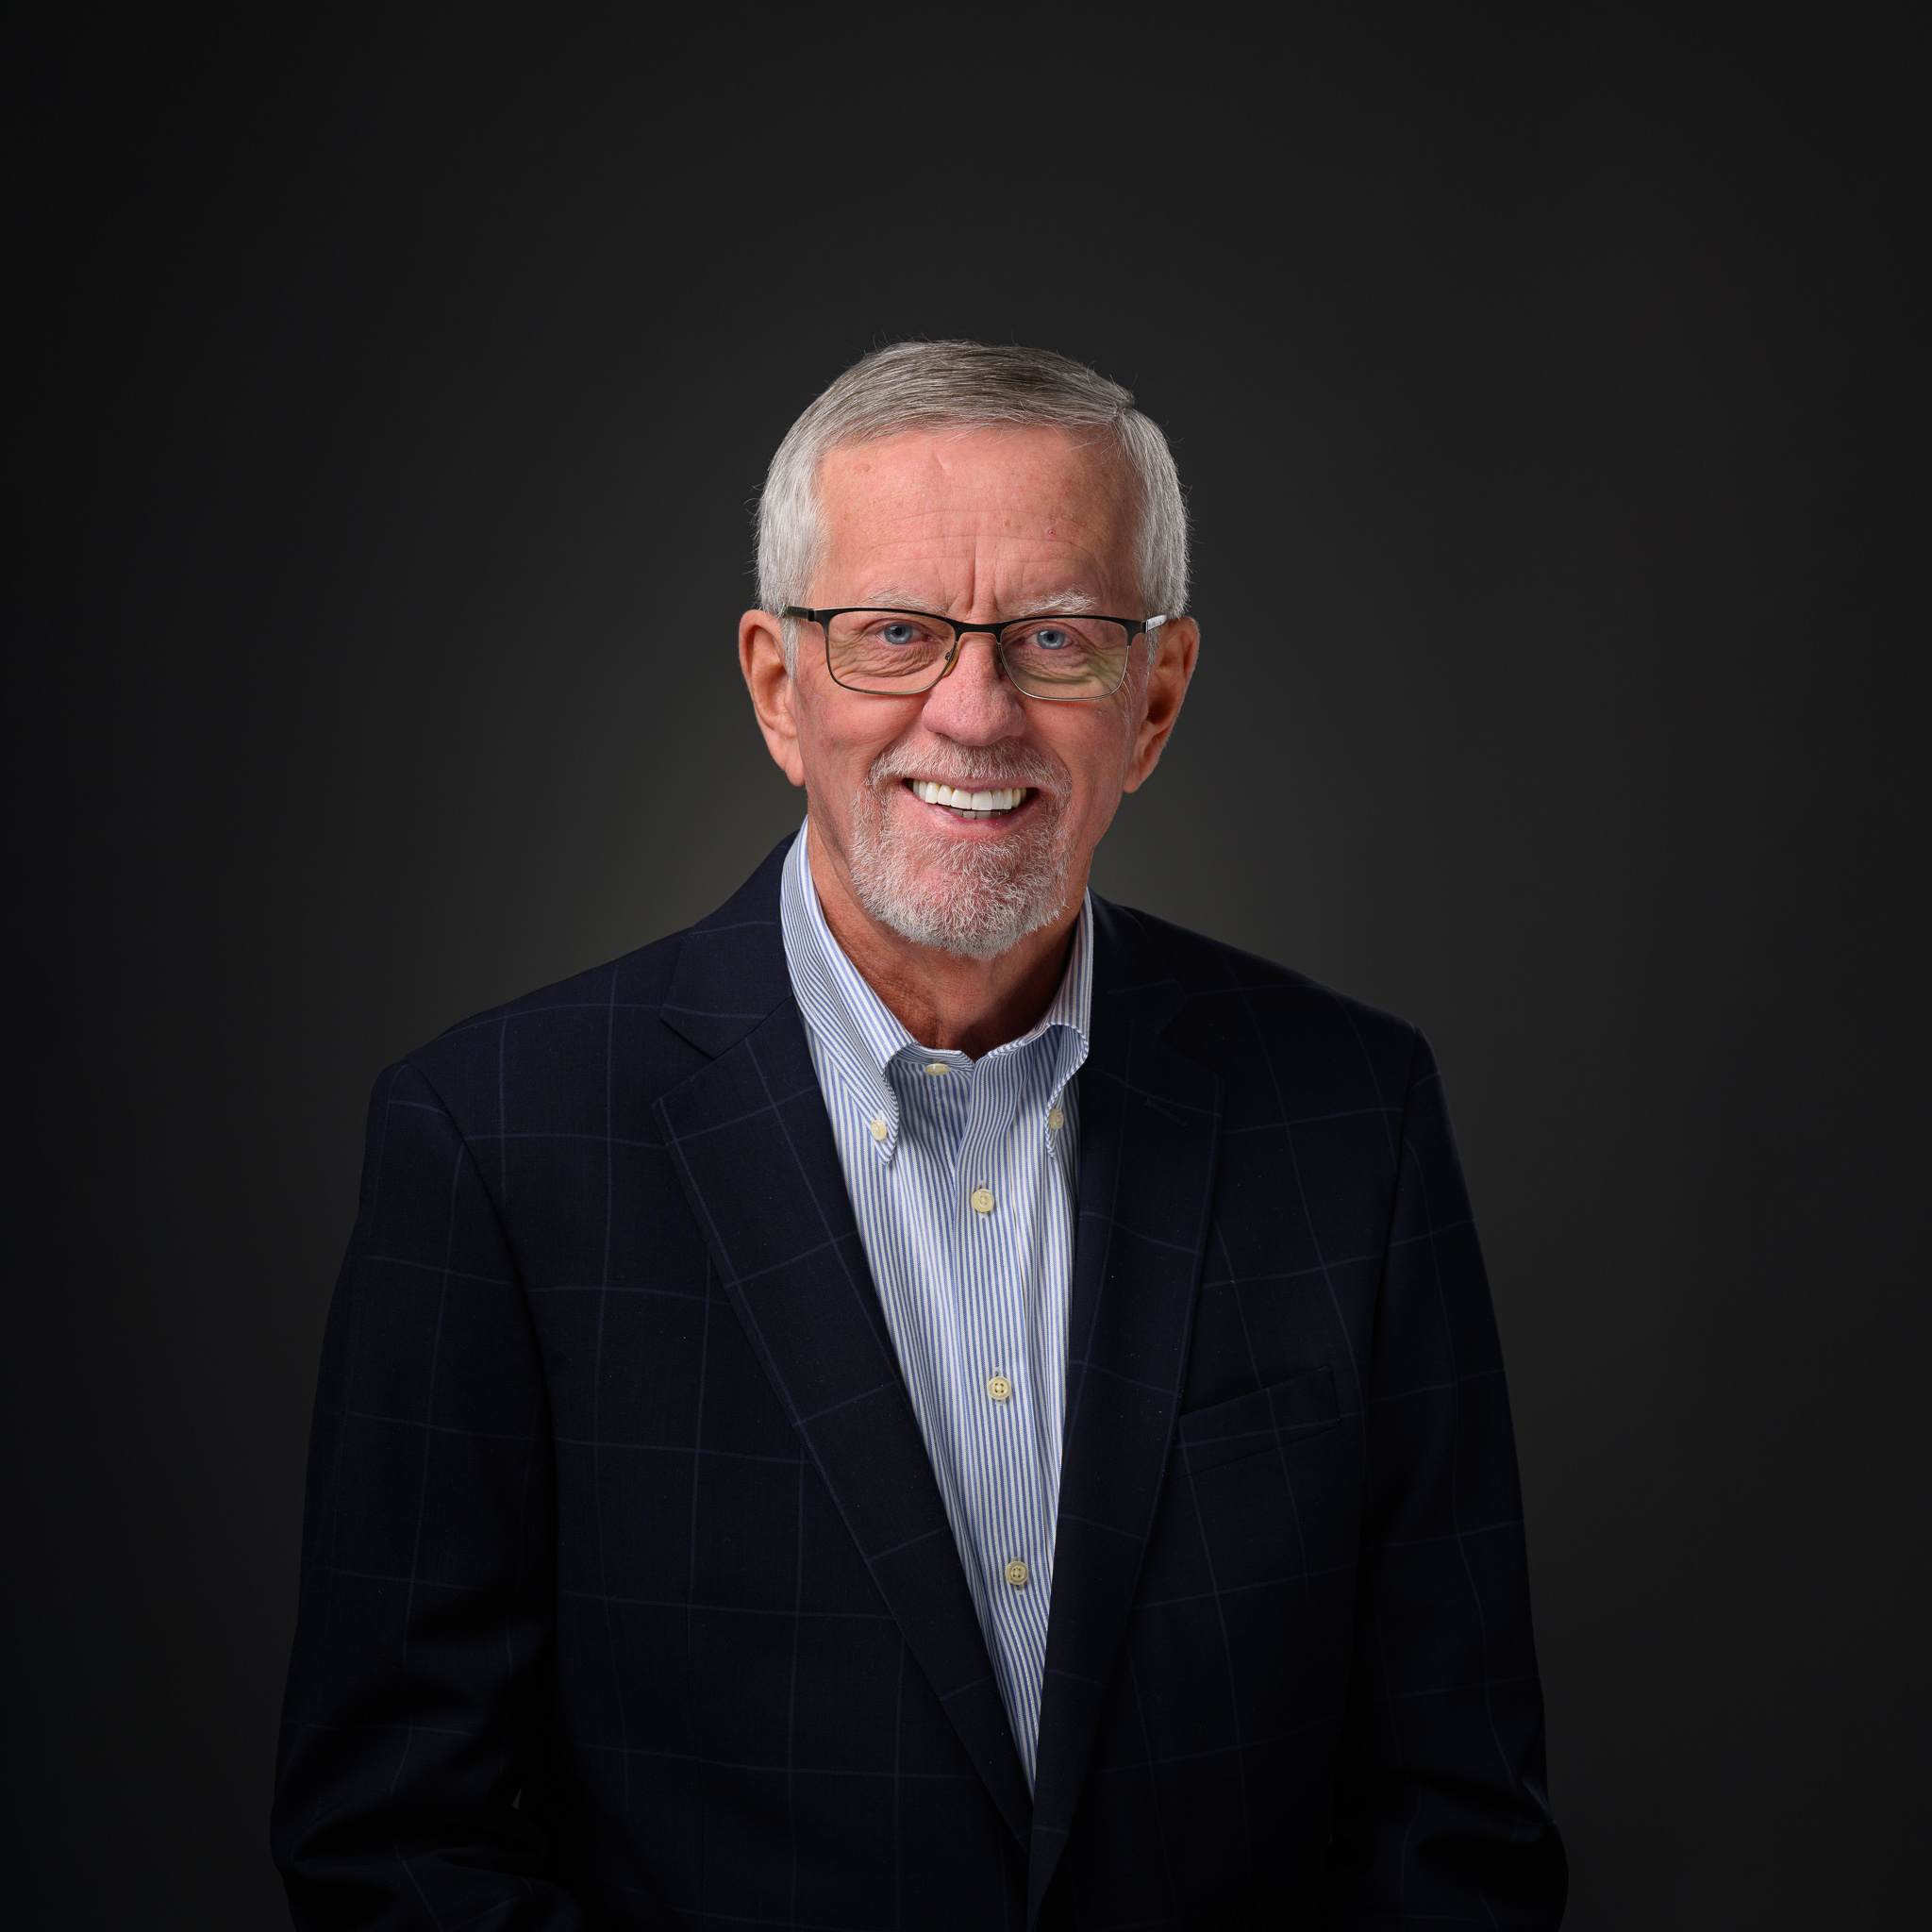
Lavern Rankin Lavern Rankin Senior Partner · Eau Claire Partners

Income protection

See Below For Disability Insurance, Explained in Plain Language

Your ability to earn is your biggest asset. Disability insurance protects it — a monthly income if illness or injury keeps you from working.

TFSA· RRSP· RESP· FHSA· RDSP· LIRA· LIF· RRIF· Pensions

What is disability insurance?

Who it's a fit for

Disability insurance pays you a monthly benefit if a sickness or injury prevents you from working. It's coverage you own personally — separate from any workplace plan — so it stays with you and is tailored to your real expenses.

Best suited for: Anyone whose household depends on their paycheque, and especially the self-employed and incorporated professionals who have no group coverage to fall back on.
The main forms of disability coverage

Individual disability insurance

What makes it different: A personally owned policy that replaces a share of your income if illness or injury keeps you from working. Definitions, waiting periods and benefit lengths are where policies differ most.

Best suited for: Self-employed professionals, business owners and anyone whose household depends on their income and whose workplace coverage is thin or non-existent.

Long-term disability (group)

What makes it different: Usually through an employer: after a waiting period, a portion of income continues while you cannot work. Coverage generally ends when employment does.

Best suited for: Employees wanting a baseline of protection through work — with a private top-up to close the gaps.

Short-term disability

What makes it different: Covers the early weeks or months of an illness or injury, often through a group plan, bridging the gap before long-term benefits begin.

Best suited for: Anyone wanting income continuity from day one of a serious illness rather than waiting out a long waiting period.

What it can do for you

  • ✓Replaces a portion of your income while you recover
  • ✓Keeps the mortgage, bills and family plans on track during a setback
  • ✓Waiting periods and benefit lengths can be tailored to your situation
  • ✓Can coordinate with workplace coverage so you're protected, not duplicated

Good to know

  • • Benefits typically replace a portion of income — not all of it — so we plan the gap together
  • • The definition of 'disability' (your own occupation vs. any work) matters enormously — I'll walk you through it
  • • Premiums, waiting periods and benefit periods all trade off — we'll balance them honestly

General information, not personal advice — details, eligibility and pricing depend on the insurer and the specific product, and are confirmed before anything is recommended.

Book a conversation

Let's talk about how you can protect and grow what YOU want.

Most people overestimate their savings and underestimate the risk. A short conversation puts real numbers on it — free, no obligation.

  • ✓ Your goals
  • ✓ Protection, investments and your tax picture
  • ✓ I will support you and provide you with honest advice at every stage of your journey
  • ✓ If retirement planning is important to you, let's map out a plan

Eau Claire Partners

Lavern Rankin is a Senior Partner with Eau Claire Partners — a full-service financial advisory firm helping Canadians build, protect and transfer their wealth with confidence.

Learn more about Eau Claire Partners